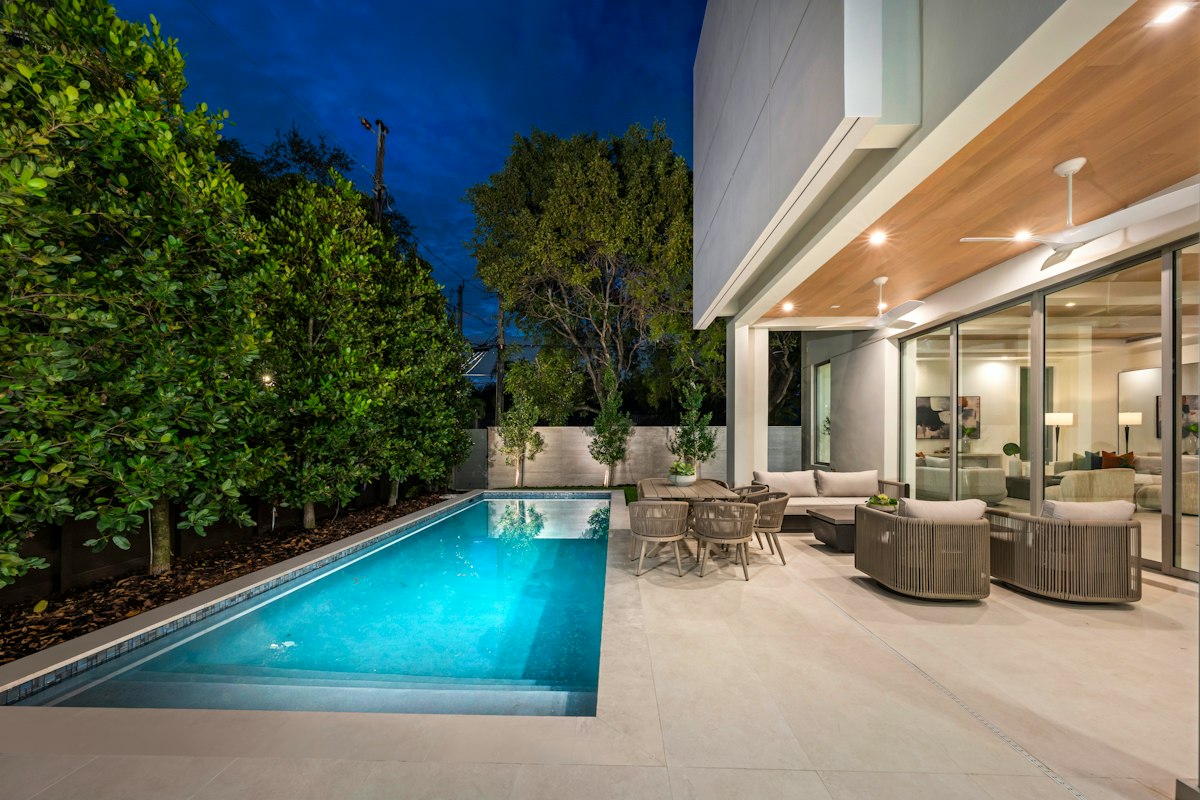
High-Value Home Financing: How to Identify the Best Jumbo Mortgage Lenders Near Me
Securing a luxury property or a home in a high-cost real estate market requires more than just a standard pre-approval letter. When the price of a home exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA), you enter the territory of jumbo mortgages. These loans are not backed by Fannie Mae or Freddie Mac, meaning lenders take on significantly more risk. Because of this, finding a local partner who understands the nuances of your specific market is often the difference between a smooth closing and a rejected application.
Many buyers start their search by looking for jumbo mortgage lenders near me because they realize that national algorithms often fail to account for regional property values and unique neighborhood trends. A local lender brings a level of expertise that a call-center-based originator simply cannot match. They have existing relationships with local appraisers who specialize in high-end homes, and they understand the property tax structures and insurance requirements specific to your area. This regional insight ensures that your loan isn't derailed by an inaccurate valuation or a misunderstanding of local market conditions.
Related posts
Selecting the Right Representation: Finding Top Real Estate Agents for Luxury Homes
Selling or buying a high-end estate isn't just a transaction; it's a sophisticated financial maneuver. When millions of...
Read more →
Real Estate Property Management Services: Operational Value, Fee Structures, and Selection Criteria
Owning investment real estate is frequently promoted as a reliable path to passive wealth, but the actual day-to-day...
Read more →
Unlocking Investment Property: Strategies to Buy Without a Down Payment
The dream of owning investment property often comes with a significant hurdle: the down payment. Many aspiring real...
Read more →
Finding the Best Commercial Real Estate Brokers Near Me: A Local Strategy for Your Next Lease or Purchase
Searching for commercial real estate brokers near me is rarely about finding a simple list of names. It...
Read more →This discussion explores the mechanics of high-balance financing, the advantages of working with local institutions, and the specific financial benchmarks you must meet to qualify. We will break down the differences between big banks, credit unions, and specialized brokers to help you determine which path fits your financial profile. By the end of this article, you will have a clear strategy for evaluating lenders and securing the most competitive terms for your high-value investment.
Whether you are a first-time luxury buyer or a seasoned real estate investor, the jumbo market demands a sophisticated approach. The stakes are higher, the documentation is more rigorous, and the underwriting process is often manual rather than automated. Understanding what local lenders are looking for—and how they differ from one another—is the first step toward moving into your new home with confidence.
Key takeaways
- Local Expertise is Essential: Local lenders provide more accurate appraisals and understand regional market volatility, which protects your earnest money.
- Higher Financial Standards: Expect stricter requirements for credit scores (typically 700+), debt-to-income ratios, and significant cash reserves.
- Diverse Lender Options: Comparing regional credit unions against national banks can reveal significant differences in interest rates and portfolio loan flexibility.
- Appraisal Accuracy: High-value homes often require two appraisals; local lenders have access to specialized professionals who understand custom features and luxury finishes.
Defining the Jumbo Loan Threshold in Your Local Market
Before you begin interviewing lenders, you must understand where the conforming limit ends and the jumbo market begins. For most of the United States, the FHFA sets a baseline limit for one-unit properties. However, in high-cost areas like San Francisco, New York City, or parts of Florida and Colorado, these limits are adjusted upward. Any loan amount that exceeds these specific county-level limits is considered a jumbo mortgage.
Because these loans cannot be sold to government-sponsored enterprises, lenders must either keep the loans on their own books—known as portfolio lending—or sell them to private investors. This lack of government backing is exactly why the requirements are so much more stringent. Lenders are essentially betting their own capital on your ability to repay a high-balance debt. Consequently, the interest rates for jumbo loans can sometimes be lower than conforming rates, but they often fluctuate based on the lender's current appetite for risk and their internal liquidity levels.
Why Searching for "Near Me" Matters for High-Balance Loans
You might wonder why physical proximity matters in a digital world. For jumbo loans, the "near me" factor is about more than just a short drive to an office; it is about market intelligence. A lender based in a different time zone might not understand why a specific street in your town commands a 20% premium over the neighboring block. A local lender, however, knows the value of that school district, the prestige of that specific gated community, or the impact of local zoning laws on property values.
The Role of Specialized Local Appraisers
One of the most common reasons jumbo deals fall through is an appraisal gap. When a home is worth millions, small percentage differences in valuation can mean hundreds of thousands of dollars. Local lenders typically work with a pool of appraisers who have spent decades evaluating high-end real estate. These professionals understand how to value custom builds, smart-home technology, and premium materials that an out-of-town appraiser might overlook. Using a local lender ensures that the person valuing your future home actually knows the neighborhood.
Relationship Banking and Custom Underwriting
Local banks and regional credit unions often prioritize relationship banking. If you already have significant assets with a local institution, they may offer you a "portfolio loan." These are custom mortgage products designed for high-net-worth individuals whose financial situations might be complex. For example, if you are self-employed or have income derived from various investments, a local underwriter can look at your total financial picture rather than just checking boxes on a standard form. This human-centric approach is a hallmark of local jumbo lending.
Comparing Different Types of Jumbo Lenders
Not all jumbo mortgage lenders are the same. Your choice will depend on your financial complexity, your timeline, and your long-term goals. Here is how the different players in the market typically operate.
National Banks and Large Financial Institutions
The biggest names in banking often have the most aggressive jumbo rates because they have massive amounts of capital to deploy. They are excellent for borrowers with straightforward W-2 income and high credit scores. However, their processes can be rigid. If your financial situation doesn't fit their specific mold, you might find the underwriting process frustratingly slow. These institutions are best for those who want the lowest possible rate and don't mind a more bureaucratic experience.
Regional Credit Unions
Credit unions are often overlooked but frequently offer the most competitive jumbo terms. Because they are member-owned and not-for-profit, they can sometimes pass savings on to you in the form of lower fees or slightly better interest rates. Many regional credit unions also have more flexible underwriting standards for long-time members. If you prefer a more personal touch and want to keep your mortgage within your community, a credit union is a strong contender.
Mortgage Brokers Specializing in High-Value Properties
A specialized mortgage broker acts as an intermediary, shopping your profile to dozens of different jumbo lenders simultaneously. This is particularly useful if you have a unique situation, such as needing a low down payment jumbo loan or having a high debt-to-income ratio due to other investments. Brokers know which lenders are currently "hungry" for jumbo business and can match you with a program that fits your specific needs. While brokers may charge a fee, the interest rate savings they find can often outweigh the initial cost.
Qualifying for a Jumbo Loan: The High Bar for Entry
While the process of applying for a jumbo loan is similar to a standard mortgage, the scrutiny is much higher. Lenders will examine every aspect of your financial life with a magnifying glass. You should prepare your documentation well in advance to avoid delays.
Credit Score and Debt-to-Income Ratios
For a conforming loan, you might get away with a credit score in the mid-600s. For a jumbo loan, most lenders want to see at least a 700, and the best rates are usually reserved for those with a 740 or higher. Your debt-to-income (DTI) ratio is also strictly monitored. While some programs allow a DTI up to 43%, many jumbo lenders prefer to see it below 36%. They want to ensure that even with a large mortgage payment, you have plenty of breathing room in your monthly budget.
Cash Reserves and Liquidity Requirements
This is where many jumbo applicants are surprised. Lenders don't just want to see that you have the down payment; they want to see that you have significant liquid assets remaining after the closing. It is common for jumbo lenders to require 6 to 12 months of "reserves." This means you must have enough cash or liquid investments (like stocks or bonds) to cover your entire mortgage payment—including taxes and insurance—for up to a year. This requirement acts as a safety net for the lender in case your income is interrupted.
Documentation for Complex Income Streams
If you are an executive with stock options, a business owner with K-1 income, or an investor with a diverse portfolio, be prepared for an intensive documentation process. Jumbo lenders will likely ask for two years of full tax returns, including all schedules. They will want to verify the stability and continuity of your income. Having a skilled CPA who can explain your tax returns to the lender can be an invaluable asset during this stage.
Strategies for Negotiating the Best Jumbo Terms
Don't assume the first rate you are quoted is the best one available. Because jumbo loans are high-profit products for lenders, there is often room for negotiation, especially if you have a strong financial profile. Consider these tactics:
- Leverage Existing Relationships: Ask your current bank if they offer rate discounts for existing customers. Many will shave 0.125% to 0.25% off the rate if you move a certain amount of assets into their management.
- Consider an Adjustable-Rate Mortgage (ARM): If you plan to sell or refinance within 5 to 10 years, a jumbo ARM can offer a significantly lower interest rate than a 30-year fixed loan.
- Pay for Points: If you have extra cash at closing, "buying down the rate" with discount points can save you tens of thousands of dollars over the life of the loan.
- Compare the APR, Not Just the Rate: The Annual Percentage Rate (APR) includes the interest rate plus fees. This is the most accurate way to compare the true cost of loans from different lenders.
Common Pitfalls in High-Value Financing
One of the biggest mistakes buyers make is opening new lines of credit or making large purchases during the underwriting process. While this is a rule for any mortgage, it is especially sensitive in the jumbo market. A new car lease or a large furniture purchase on credit can shift your DTI just enough to trigger a denial. Additionally, ensure your down payment funds are "seasoned" in your account for at least 60 to 90 days. Large, unexplained deposits can cause significant delays as lenders must verify the source of every dollar to comply with anti-money laundering regulations.
Frequently Asked Questions
What is the minimum down payment for a jumbo loan?
While the traditional requirement was 20% down, many lenders now offer jumbo loans with as little as 10% or 15% down for highly qualified borrowers. Keep in mind that a lower down payment usually results in a higher interest rate and may require private mortgage insurance (PMI).
Are jumbo mortgage rates higher than conventional rates?
Not always. Depending on market conditions and lender liquidity, jumbo rates can actually be lower than conforming rates. This happens because jumbo borrowers typically have higher credit scores and more assets, making them attractive customers for banks looking to build long-term relationships.
Can I use a jumbo loan for an investment property?
Yes, but the requirements are even stricter. Expect to put down at least 25% to 30% and pay a higher interest rate compared to a primary residence. Lenders will also want to see a history of property management or a very strong balance sheet.
How long does it take to close on a jumbo mortgage?
Generally, you should allow for 45 to 60 days. The manual underwriting process and the potential need for two separate appraisals mean that jumbo loans take longer to process than automated conforming loans. Working with a local lender can sometimes speed this up due to their direct access to local professionals.
Do I need two appraisals for a jumbo loan?
For very high loan amounts—typically those exceeding $1.5 million or $2 million—many lenders require two independent appraisals from different companies to confirm the property's value. This is a standard risk-mitigation step in the luxury market.
Conclusion
Navigating the world of high-value real estate requires a strategic partnership with a lender who understands the complexities of the jumbo market. By focusing on jumbo mortgage lenders near me, you tap into a wealth of local knowledge that protects your investment and ensures a smoother path to homeownership. Remember that the lowest interest rate isn't always the best deal if the lender cannot execute the loan or if their appraisal process is flawed. Prioritize lenders who offer a balance of competitive pricing, local expertise, and a transparent underwriting process. With the right financial partner and a well-prepared application, you can secure the financing necessary to claim your piece of the high-end market.